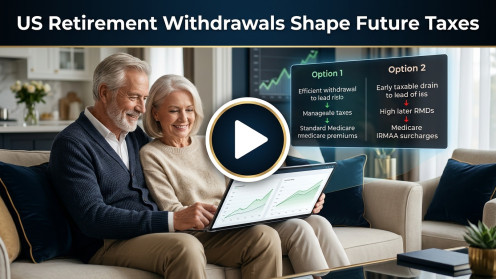
When it comes to retirement planning, the way you manage withdrawals can have a big impact on your future tax landscape—and your Medicare costs. For example, two retirees with identical $2.1M portfolios might end up with very different tax bills, all because of how they handled early withdrawals, required minimum distributions (RMDs), and the timing of their Medicare surcharges. If your savings are split between taxable accounts and a traditional IRA, it’s not just the total income—$117.4K per year in this case—that matters, but also how your assets are positioned. For 2026 joint filers, keeping your modified adjusted gross income at or below $218K means you’ll stay with standard Medicare premiums. But even one dollar over could trigger higher Part B premiums (nearly $284) plus extra Part D charges. Choosing to spend down taxable accounts first might let your IRA grow, but that can lead to bigger RMDs later. On the other hand, planning IRA withdrawals or conversions before you hit RMD age could ease future tax and Medicare pressures. As the end of the year approaches, it’s wise to model different RMD strategies, keep an eye on conversion amounts to avoid IRMAA cliffs, and take a look at your IRA holdings for risks like floating-rate investments, leverage, or concentration. My passion is helping Medicare members navigate these complex decisions so they can feel confident about their financial future.
Leave a Reply